
To pave the way for balance sheet reduction, US regulators significantly relax bank capital requirements

On March 19, the Federal Reserve, the Federal Deposit Insurance Corporation (FDIC), and the Office of the Comptroller of the Currency (OCC), the three major U.S. regulatory agencies, jointly launched a new round of bank capital rule reform proposals aimed at easing capital constraints within the U.S. banking system. Specific measures include: First, making fundamental revisions to the contentious Basel III Endgame rules, eliminating some issues of double counting and improving the accuracy of risk weights; second, adjusting the G-SIB surcharge by pegging it to nominal GDP and reducing the buffer capital size (previously 50 basis points, now reduced to 10 basis points); third, relaxing constraints related to the Supplementary Leverage Ratio (SLR); and fourth, reforming the stress testing mechanism to improve transparency and reduce uncertainty in capital requirements.
After consolidating the Basel III Endgame rules, stress test reforms, and global systemically important bank (G-SIB) surcharge adjustments, the minimum Common Equity Tier 1 (CET1) capital requirements for large U.S. banks (assets over $700 billion) are expected to decrease by approximately 4.8%, medium-sized banks (assets between $100 billion and $700 billion) by 5.2%, and small banks (assets less than $100 billion) by as much as 7.8%. If previously implemented stress test reforms and leverage ratio adjustments are also considered, the amount of capital freed up for large banks could reach tens of billions of U.S. dollars.
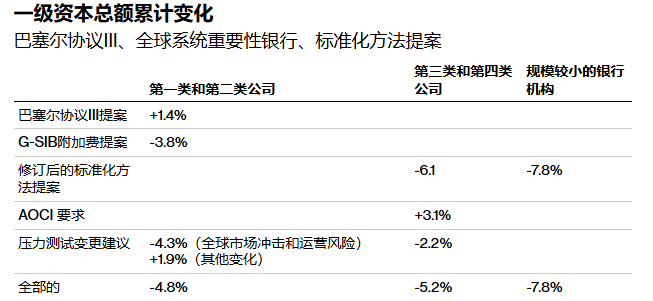
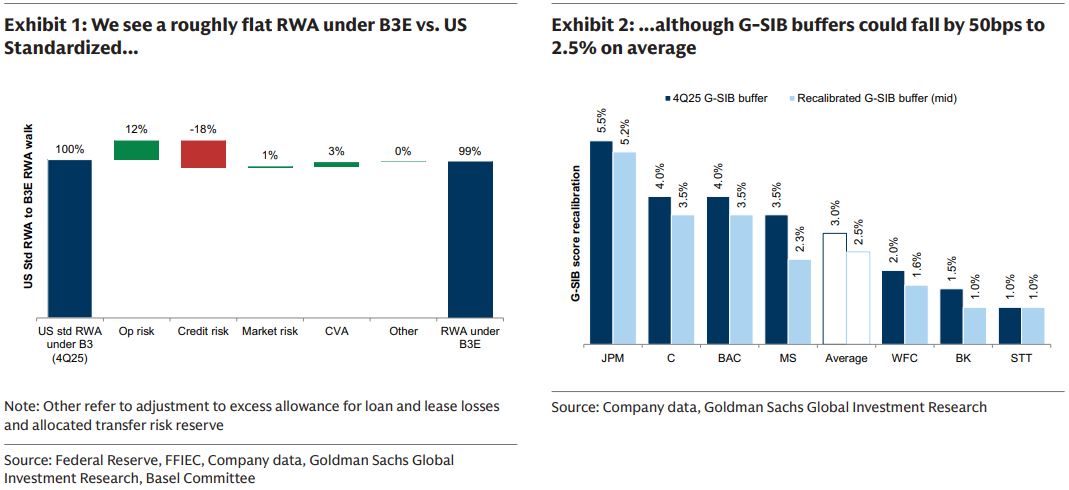
From a policy perspective, this round of reform will be the largest relaxation of capital rules since the 2008 financial crisis. In addition to directly modifying capital rules, regulatory focus is also simultaneously shifting towards liquidity requirements. Federal Reserve Vice Chair for Supervision Bowman and U.S. Treasury Secretary Besant have publicly advocated for adjustments to key liquidity rules (such as LCR and ILST), proposing to include banks’ capacity to obtain funding through channels such as the Federal Reserve discount window as part of high-quality liquid assets (HQLA), thereby reducing banks’ over-reliance on traditional liquidity buffers.
Loosening Regulation and Paving the Way for Balance Sheet Reduction
The direct effect of this policy round is to free up bank capital space and promote credit expansion. Wall Street banks will be able to release tens of billions of dollars in funds to expand lending, increase share buybacks, and boost shareholder dividends. In this process, traditional commercial banks and mega-regional banks will disproportionately become the main beneficiaries. The proposal significantly reduces the risk weights for residential mortgages and corporate loans; for example, the risk-weighted assets (RWA) of residential mortgages at small and medium-sized banks are expected to decrease by about 30% to 31%. Such structural tilting will markedly enhance the willingness and capacity of traditional lending institutions to expand their balance sheets.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Prospects for the opening of the Hormuz Strait are overshadowed, Asian bonds under pressure: 2Y Japanese bond yield approaches 2%, 3Y Korean bond yield rises to highest level since 2022
With high oil prices, short-term bond yields in South Korea and Japan have risen.
5% US Treasury pressure weighs on global assets, while Australian government bonds open up a window for allocation? Fixed income giant Pimco calls the rate hike expectations too aggressive
Pacific Investment Management Company (Pimco) holds a constructive view on Australian bonds, believing that market expectations for rate hikes are too high. Pimco stated that the rate hike cycle in Australia has been "fully priced in," and cracks are beginning to appear in the economy, making Australian bonds look attractive, especially in the 5- to 10-year segment of the yield curve.
Only a few stocks are rising! Goldman Sachs warns: US stock market breadth hits the worst level since the 2000 internet bubble, with rare divergence in bond volatility
Flood, a Goldman Sachs partner, believes that leading AI companies are propping up the market indexes, while median stocks have fallen 16% from their highs. More unusually, Garrett, the head of derivatives trading at Goldman Sachs, warns that the bond volatility MOVE index is at an extremely high percentile, yet the VIX remains subdued. Jonathan Krinsky, a strategist at BTIG, points out that while total hedge fund leverage is rising, net leverage is falling, indicating a contradiction of "increasing exposure without increasing direction," and warns: "Something has to give."
Hyperliquid’s big test: Can institutional demand absorb $100M in whale selling?
Crypto prices
More


