
Indonesian Rupiah in the Mire

As the largest economy in Southeast Asia, Indonesia’s Jakarta Composite Index has plunged 29% since the beginning of this year, with the Indonesian rupiah depreciating against the US dollar by more than 6%. Frequently facing the “triple shock of stock, bond, and foreign exchange markets,” Indonesia has, over the past six months, undergone a “defense of an emerging market seat” turmoil. In January this year, MSCI announced a freeze on all index rebalancing for Indonesia, no longer adding Indonesian stocks to the emerging market index, while issuing a heavy warning: the Indonesian market has fundamental investability flaws, and if required reforms are not carried out in time, Indonesia will be downgraded from an emerging market to a frontier market.
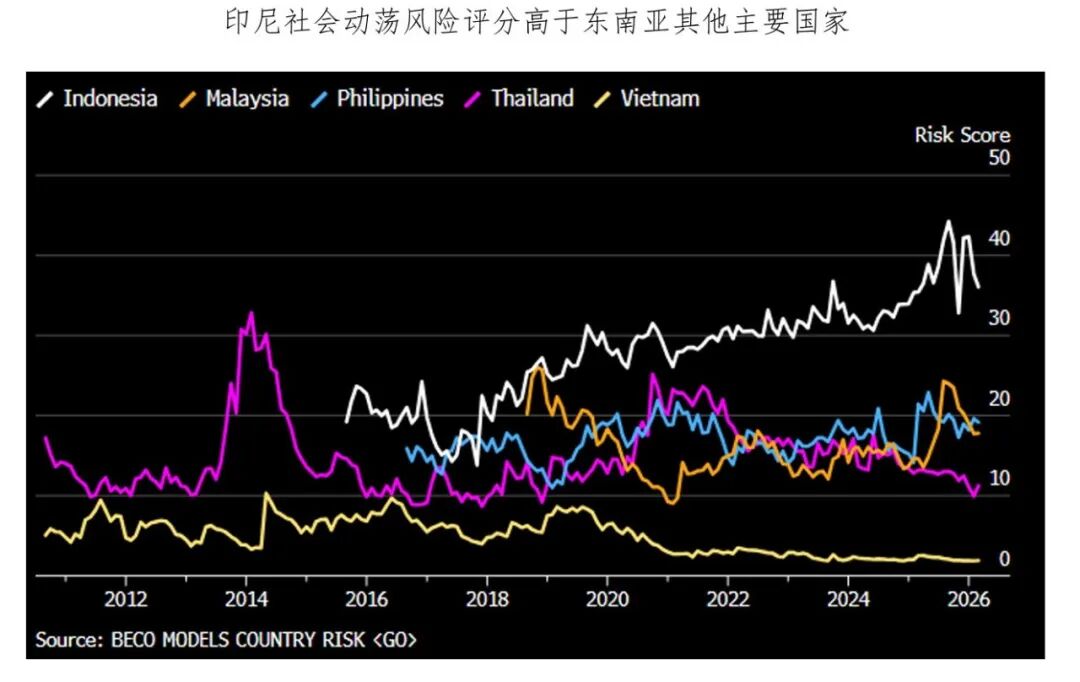
Last week, MSCI’s final decision was to maintain the rating, but downgraded the “information flow” sub-rating to negative. Indonesia’s central bank’s 100BP rate hike within less than a month also led the rupiah to recover from historic lows. But has the crisis really been resolved?
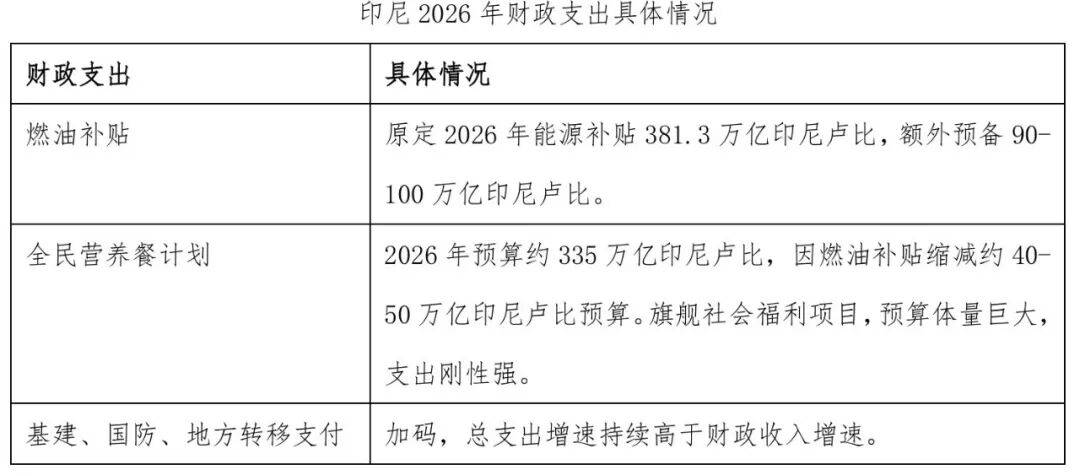
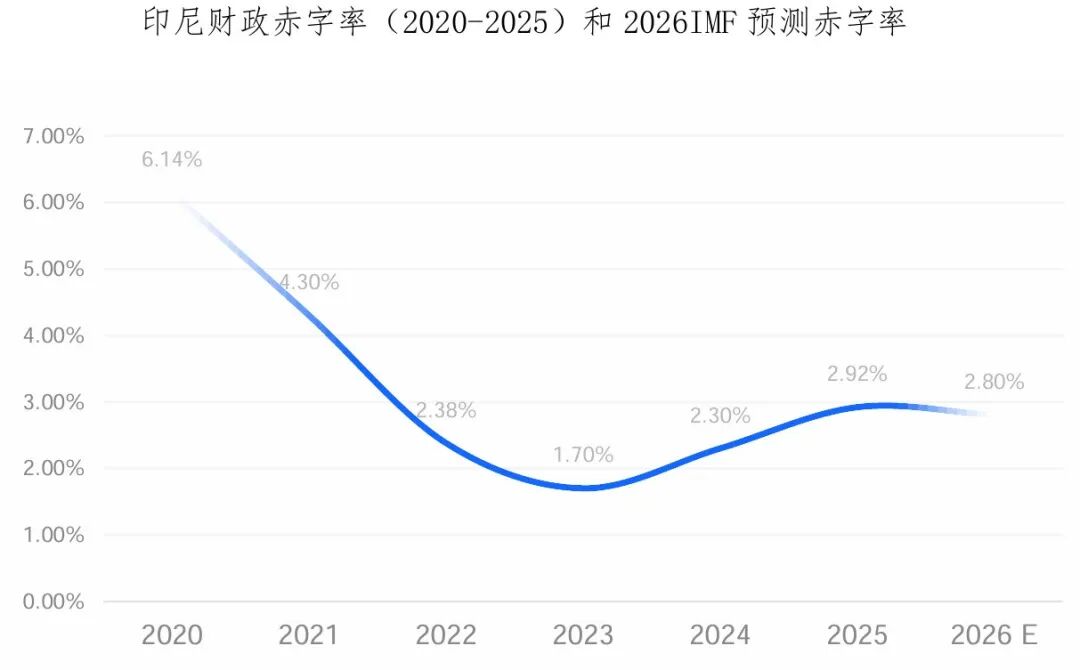
Fiscal deficit remains elevated, exchange rate under pressure. Indonesia’s “State Budget Law” strictly caps the fiscal deficit ratio at 3% and the government debt ratio at 60%. In 2025, Indonesia’s fiscal deficit ratio will rise to a post-pandemic high (the ceiling was temporarily lifted during the pandemic). Since the US-Iran conflict, rising international oil prices have forced increased fuel subsidies alongside rollouts of nationwide nutrition programs and infrastructure construction. With persistently high fiscal expenditures and sluggish fiscal revenue growth, there is doubt in the market about the balance and sustainability of Indonesia’s public finances.
Net oil imports have weighed on exchange rates since the US-Iran conflict. In comparison, both Brazil and Indonesia are commodity-exporting emerging economies, but their currencies have performed differently. Comparing their trade structures, Brazil, benefiting from its deepwater oil technology, is a net exporter of crude oil, whereas Indonesia, though running a surplus in goods trade (mainly coal, palm oil, and ferronickel), suffers a natural deficit in oil and gas, as energy heavily relies on imports. Since the US-Iran conflict, the rise in oil prices has led to greater divergence in the currency movements of the two countries.
In the report “Defense War of Asian Currencies”, we’ve already introduced how, since the beginning of this year, Bank Indonesia has directly intervened by using forex reserves and implemented some macroprudential and capital control measures. Coupled with ongoing rate hikes since May, these have only temporarily relieved pressure on the rupiah, while the fundamental causes of its depreciation remain unchanged:
(1) The fiscal deficit is expanding with the deficit ratio remaining high; rate hikes and further depreciation are likely to increase fiscal pressure;
(2) The newly introduced strategic resource export SOE monopoly policy (where companies under the sovereign wealth fund are the sole legal intermediaries for exporting coal, palm oil, titanium alloy, etc. to overseas buyers) was intended to enhance fiscal revenue but has sparked market debate, and could negatively impact exports. Coupled with long-standing net energy imports, trade uncertainty has increased.
BFC Exchange Talk
With you through 2026
Welcome to leave us a message in the background
Communicate with us
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
US Treasury yields soar to a 24-year high; US Treasury advisors expect future declines as AI investments and energy shocks drive up borrowing costs
David Zervos, senior advisor to U.S. Treasury Secretary Yellen and a veteran Wall Street professional, stated on Thursday that despite the recent surge in U.S. Treasury yields to their highest levels in decades, the current real yields are significantly elevated compared to historical levels, suggesting room for a decline in the future.
St. Louis Fed President: Further rate hikes needed over the next 6 to 9 months; inflation remains the top issue for the US economy
St. Louis Federal Reserve President Musalem said on Thursday that the Federal Reserve still needs to raise interest rates further in order to bring U.S. inflation back to the 2% target in a timely manner.
Trump's tariffs increase U.S. consumer costs: New York Fed reports prices of related goods up nearly 3%, impact may last until 2027
The latest research by the Federal Reserve Bank of New York shows that the tariff policies implemented by U.S. President Trump have significantly increased the cost for American consumers to purchase everyday goods.
Overnight US Stocks | AI Performance Concerns Resurface, Nasdaq Falls Over 1%, Micron Technology (MU.US) Drops Over 4%
At the close, the Dow Jones Index rose by 52.61 points, or 0.10%, to 51,232.48 points; the S&P 500 Index fell by 36.35 points, or 0.47%, to 7,765.42 points; and the Nasdaq Composite Index dropped by 345.35 points, or 1.25%, to 27,193.34 points.
Crypto prices
More


