
Oil prices fall to pre-war levels, why aren't US interest rates following?

Morning FX
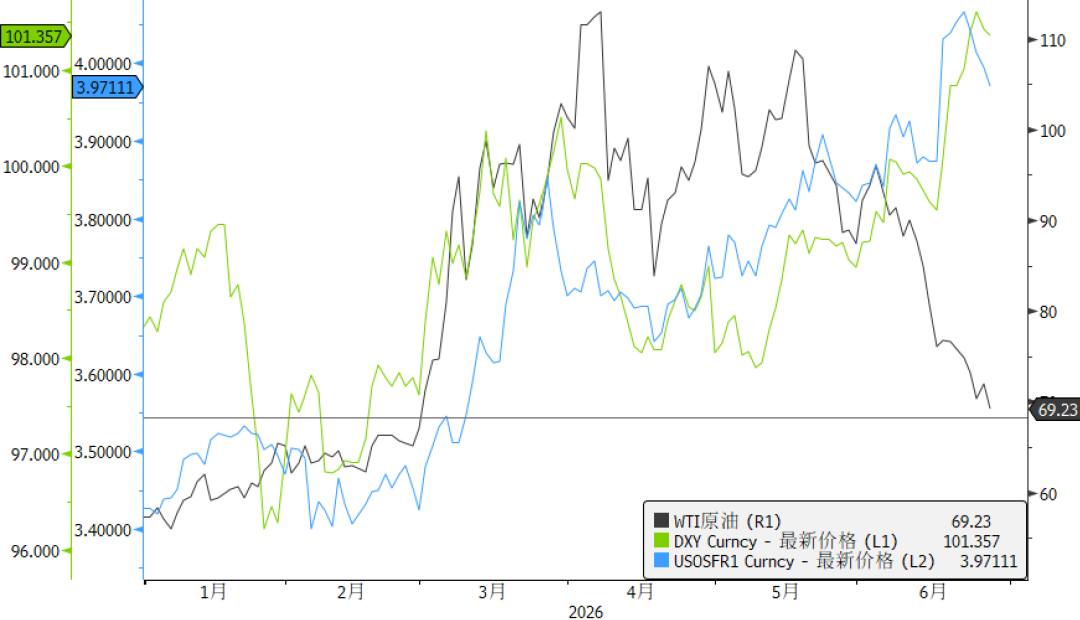
Since the US-Iran deal was reached, the price of the two international crude oils has quietly approached early March levels, exceeding market expectations. At the same time, 1Y SOFR has continued to rise since May, moving in the opposite direction of oil prices. Why doesSOFRignore the drop in oil prices?
1. Counter to expectations: Why did oil prices fall so fast?
Shortly after the US-Iran war began in March, the entire market was flooded with concerns that international oil prices would remain high throughout the year, with many believing $100 per barrel would be the floor, and Bank of America even set the peak at a terrifying $150-$200. However, reality proved otherwise: since May, the two international oils have been declining, and are now near pre-war levels.
Why did oil price trends differ so much from market expectations? I believe JP’s recent review of crude oil gave a pretty clear explanation:
Under the energy supply shock caused by the war, there are two ways for the market to clear,
"First, assuming overall demand remains unchanged, supply shortage causes prices to soar. In the short term, the market can make up for shortages by drawing down inventories, but in the medium and long run, accumulating consumption and restocking demand will make it even harder for oil prices to come down over time."
This was the expectation of most market participants at the start of the war, but the truth is that the decline in commercial inventories was not as steep as expected, while demand loss was much greater than anticipated. This leads to another path for market clearing:
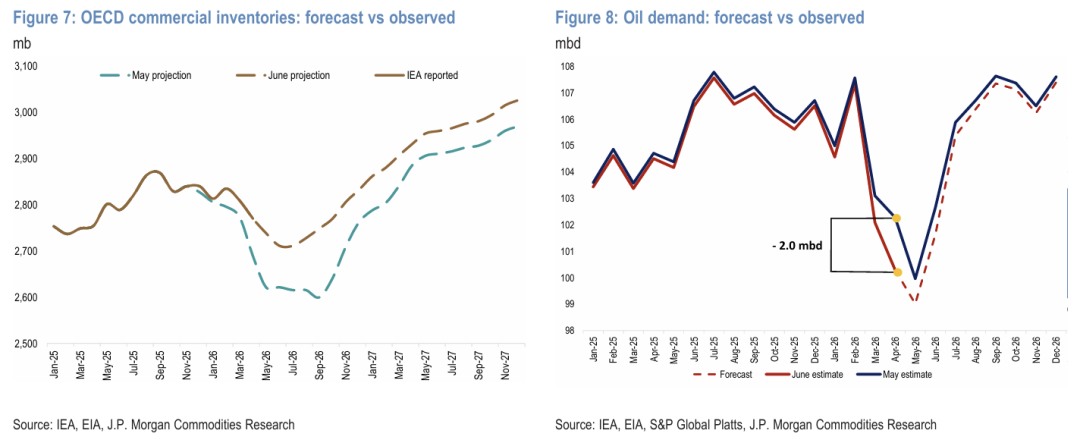
"Second, when there is a supply shortage, demand rapidly shrinks as well, which in turn pressures oil prices." JP particularly emphasized how quickly Asia (especially China) has adjusted its demand for oil since the conflict, and of course, the rapid development of new energy fields played a significant role.
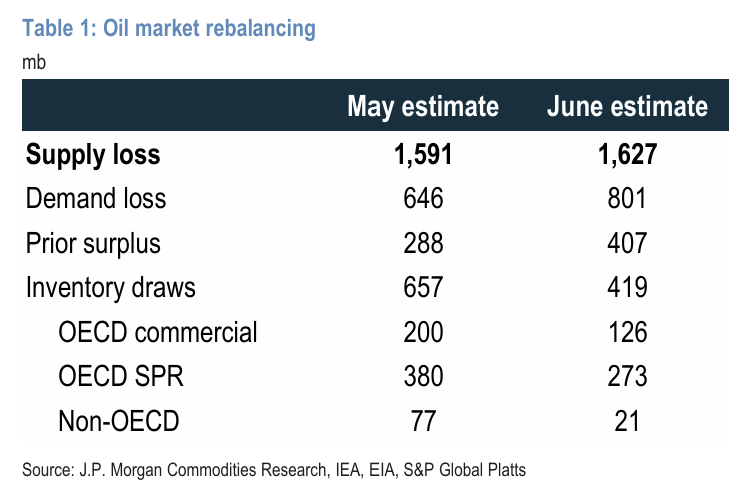
Here I will share JP’s conclusion with everyone:“The market will always clear, but the path the market takes to get there is the key to where the price finally settles”.
2. Counterintuitive: Why do US interest rates ignore falling oil prices?
Before May, oil prices and 1Y SOFR were quite correlated, but after mid-May their correlation fell sharply, which is actually counterintuitive. After all, the recent rise inSOFRhas mainly been based on the logic of “rising oil prices - higher inflation - higher policy expectations.” So why do they rise together but not fall together?
I believe there are two main reasons for the current divergence between oil prices and US interest rates: first, the US macroeconomic fundamentals are indeed strong, with two consecutive months of nonfarm payroll data beating expectations and the PMI ranking the highest in the G10. Second, the new Fed chair, Waller, made his first appearance by dropping a hawkish bombshell, vowing to achieve the 2% inflation target that hasn't been met for more than five years. Given his style of refusing policy guidance, the market had no choice but to add more uncertainty premiums to his hawkish signals.
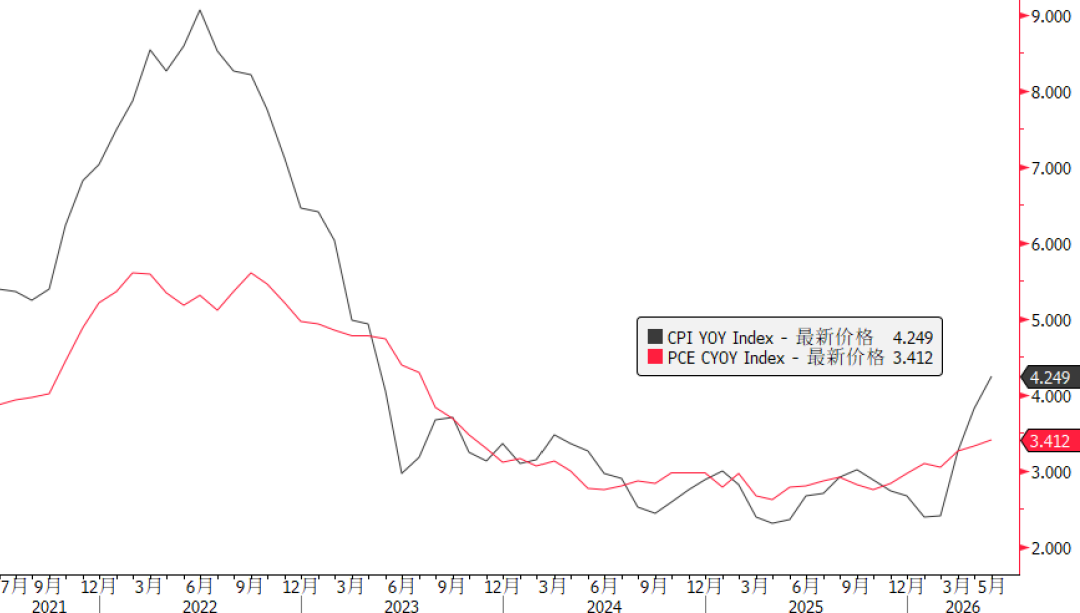
Therefore, under the current circumstances, US interest rates might maintain this tendency of "following oil price hikes without following declines." Unless (1) oil prices stabilize below 80 and US CPI falls to below 3% after a few months, or (2) the US stock market crashes and the fed put is forced to come online, it will be difficult for short-term US rates to fall sharply.
3. Summary
International oil prices fell to pre-war levels, possibly because demand contracted faster than supply dropped, leading the market to a clearing path that was completely different from the initial expectations.
SOFR “rises with oil but doesn’t fall” for two main reasons: solid US fundamentals and Waller’s hawkish stance. For SOFR to fall sharply, we may have to wait for a significant decline in US CPI or a stock market crash.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Vistagen stock surges 54% to $0.54, but RSI near 90 signals overbought
Update 1 - US 30-Year Mortgage Rate Surpasses 7%, Reaching Two-Year High
ETF inflows meet CTA liquidation: Who is pricing gold?
Crypto prices
More


