
Dip buying and internal disagreements within the Federal Reserve help push gold prices higher, but the upside is likely to be limited.

Fxstreet July 9 News—— On Thursday (July 9) during the European session, international gold saw a mild rebound as a large number of bottom-fishing investors optimistic about medium- and long-term gold prices gradually entered the market, putting an end to the previous three consecutive days of decline. Many investors believe that the recent decline has excessively released bearish pressure, and gold prices have now entered a value allocation range. This is the main short-term driving force for the stabilization and rebound in gold prices.
On Thursday (July 9) during the European session, international gold saw a mild rebound as a large number of bottom-fishing investors optimistic about medium- and long-term gold prices gradually entered the market, putting an end to the previous three consecutive days of decline. Many investors believe that the recent decline has excessively released bearish pressure, and gold prices have now entered a value allocation range. This is the main short-term driving force for the stabilization and rebound in gold prices.
After the release of the Federal Reserve's June FOMC minutes, the US Dollar Index fell slightly. The hawkish tone in the minutes was somewhat lower than some market participants’ earlier pessimistic expectations. However, geopolitical risks remain significant. The renewed escalation between the US and Iran continues to support high international crude oil prices, driving global concerns about prolonged elevated inflation. Gold itself does not generate interest income, and a high inflation environment forces the Federal Reserve to maintain a tightening policy stance, which significantly limits the upside ceiling for precious metals prices.
The minutes showed severe divisions within the Fed, with policymakers evenly split over whether to continue raising rates. Nine officials anticipate at least one more hike before year-end, while the other nine favor keeping rates unchanged. This internal division makes it difficult for the market to predict the Fed's future policy direction, causing investors to wobble between expectations of loosening or tightening monetary policy and resulting in uncertain risk-aversion sentiment in the market.
Although the minutes did not materially reinforce the case for further rate hikes, they also released very few dovish signals to support rate cuts. This shattered the market’s earlier optimism for a rapid rate-cut cycle later this year. Market participants are now focusing entirely on upcoming US economic indicators, waiting for data to provide clearer guidance.
Currently, the market prices in about a 65% chance of a Fed rate hike in September. Meanwhile, renewed geopolitical tensions in the Middle East will continue to drive energy prices higher, adding further uncertainty to inflation trends and presenting new challenges for the Fed’s policy decisions. If crude oil prices continue to surge, it will be very difficult for the US CPI to return to the 2% target, and the Fed will be forced to maintain its hawkish stance, which is a long-term bearish factor for gold.
Given these factors, real yields and the Dollar Index are unlikely to fall sharply in the short term. The strong dollar is difficult to reverse, and gold's competitive disadvantage compared to yield-bearing assets will persist. This makes it hard for gold prices to launch a sustained and strong rebound, and any recovery is likely to be limited.
The market will next focus on US initial jobless claims data and public speeches from several Fed officials. Such labor market data reflect the health of the US labor market, while officials’ comments can reveal their latest views on rate hikes and inflation, providing key clues for future monetary policy outlook. In addition, developments in the Middle East will continue to be closely watched by investors; if oil prices rise further, inflation concerns will be exacerbated, putting additional pressure on gold’s potential for gains.
Technical Analysis
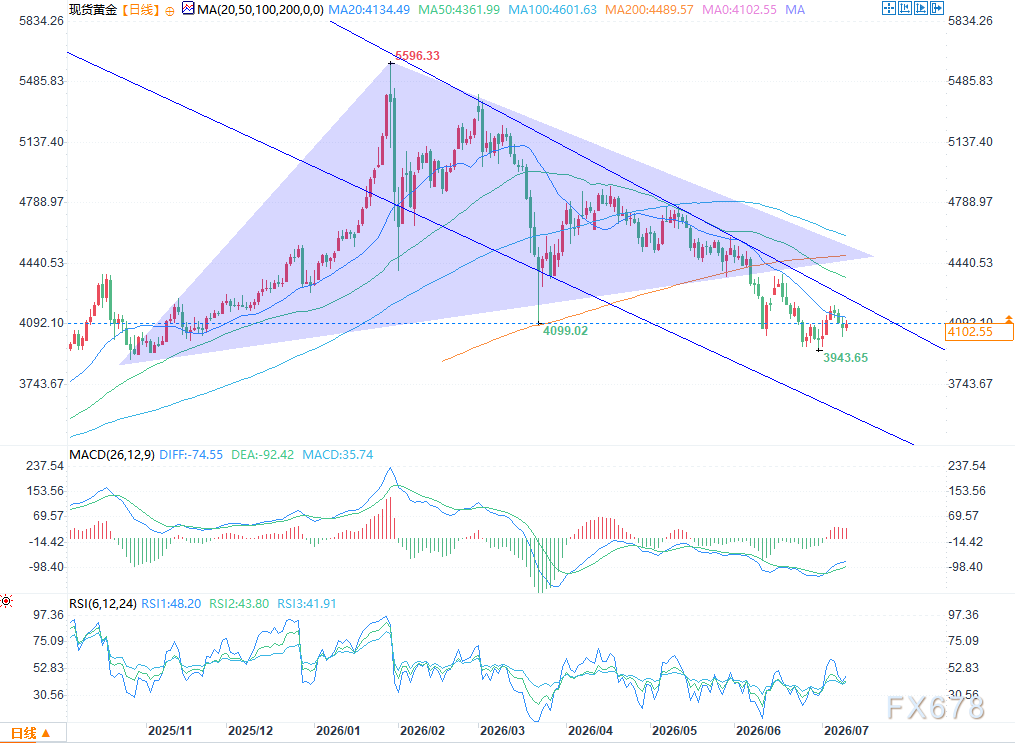
(Spot gold daily chart Source: Fxstreet)
After gold prices broke below the symmetrical triangle pattern and the 200-day moving average, they fell all the way to near the 3940 low, hitting the lowest level since October last year. After the bulls’ support lines were repeatedly breached, a large number of programmed stop-loss orders were triggered, which intensified the previous drop in gold prices.
Although gold prices have temporarily stabilized, they are still trading below the downtrend line, the 50-day, and 200-day moving averages, with the medium- to long-term technical pattern remaining bearish. All moving averages are exerting downward pressure from above, and the medium-term bearish trend has not reversed just because of the short-term rebound.
Bearish traders will wait for gold prices to break below the key level of 3940, creating a new stage low. At that point, prices will likely further test the strong support level at 3800. If the 3940 support fails, bearish market sentiment will deepen and the downside space will be fully opened.
If gold prices start to rebound, they must first hold above the 4100 level before attempting to break 4200, which is exactly where the downtrend line and resistance converge. Successful breakout of this zone will target 4370 next, and then the 50-day moving average near 4500. Only by steadily holding above 4500 can gold escape medium-term bearish pressure and gradually return to an upward channel.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Nvidia’s Record Run Signals Another AI Wave: 5 Cryptos Worth Buying Before the Breakout
Apple (AAPL.US) Teams Up with LG to Enter Smart Home Market: Accessories such as doorbells, thermostats, and cameras to feature LG branding
According to sources, Apple is set to expand its smart home device lineup, including doorbells, thermostats, and other accessories. These products will be developed through an unusual partnership between Apple and LG Electronics.
Review Article - ROI - For Trump's Treasury, the "tail" of the auction is the toughest part: McKeever
Repeated, no changes to the main text. By Jamie McGeever Reuters, Orlando, Florida, October 6 - U.S. Treasury auctions are supposed to be dull, predictable, and lacking in news value. But these are unusual times, and the Trump administration now faces the risk of weak government bond sales making headlines. The U.S. Treasury plans to issue nearly $120 billion in bonds this week—the first auction of bonds other than short-term Treasury bills in two weeks: $58 billion in three-year notes on Tuesday, $39 billion in ten-year notes on Wednesday, and $22 billion in thirty-year bonds on Thursday. These auctions would ordinarily be inconsequential, but they're attracting increased attention due to the exceptionally weak auction results from September 22–24—particularly the five-year Treasury auction on September 23, which led to the largest jump in yields since April of last year. Since then, yields have not fallen back, and instead, have surged to multi-decade highs across most maturities. It's important to note that the possibility of a "failed" U.S. Treasury auction is nearly zero. The primary dealers—26 banks and institutions currently authorized by the New York Fed to act as Treasury market makers on Wall Street—are always involved. They essentially underwrite the sales, ensuring the smooth operation of the $30 trillion U.S. Treasury market, which is the most liquid in the world. This, in turn, keeps the entire global financial system running. Trillions of dollars of global debt, assets, and market derivatives are benchmarked off U.S. Treasuries. U.S. Treasuries also serve as collateral to "lubricate" the pipes of the U.S. and global financial systems—in repos, interbank lending, and financing. In short, as long as U.S. Treasuries remain the backbone of the global financial system, there will always be buyers in Treasury auctions. The perpetual question is the price at which these bonds ultimately clear. With borrowing costs in the secondary market now at their highest since the mid-2000s, it's reasonable to expect the Treasury will pay correspondingly high rates in the primary market. But as recent auction rounds have shown, there remains potential for negative surprises. “Too big for the market to digest?” The $70 billion five-year auction on September 23 was among the most concerning in recent years. Demand—as measured by bid-to-cover ratio—was the lowest in nine years. The Treasury sold these notes at a yield of 5.033%, more than 3 basis points above the market yield at the auction deadline. Three basis points might not sound like much, but for a five-year Treasury auction, that's highly unusual. This was the largest so-called "tail" since June 2022. JP Morgan analysts pointed out that the last time the five-year auction saw a three-basis-point tail was back in 2011—when the brewing debt ceiling crisis ultimately led to the U.S. credit rating being downgraded that August. Back to today, concerns over the U.S.'s bleak fiscal outlook have pushed up long-term borrowing costs. Consequently, markets widely expect the Trump administration to gradually shift the Treasury's massive funding needs toward the lower-cost, shorter end of the yield curve. That explains why the five-year auction two weeks ago caused such a stir. A three-basis-point tail is common in long-bond auctions, but rare for securities in the so-called "belly" of the curve. If the Treasury is forced to pay a higher premium to move these bonds, then Houston, we have a problem. Large auction tails can be caused by numerous factors, such as market volatility on the day of the auction or, more worryingly, underlying fundamental issues that could erode demand over time. It's usually difficult to distinguish between these dynamics, as they're not mutually exclusive. On the brighter side, this unease hasn't yet spread to the short end of the curve. At least, not for now. Three- and ten-year Treasury yields have risen by about 50 basis points from the last auction a month ago, hovering around 4.96% and 5.32% respectively. The 30-year yield is up about 35 basis points, to 5.65%. That should be high enough to attract strong demand and ensure smooth sales, right? Probably. But if we get a surprise, volatility and uncertainty could ripple across the entire market. Investors will be… watching developments like hawks. (The views expressed herein are those of the author, a Reuters columnist.) Enjoyed this column? Visit Reuters Open Interest, your essential new source for global financial commentary. Follow ROI on LinkedIn and X. You can also listen to the daily "Morning Bid" podcast on Apple, Spotify, or the Reuters app. Subscribe for seven-day-a-week in-depth analysis of market and financial news by Reuters journalists. US 5-year auction has biggest 'tail' since 2022 https://fingfx.thomsonreuters.com/gfx/mkt/dwpkmkzogpm/TAIL.png (For reader convenience, Reuters automatically translates its reports into several other languages. Automate
Will cancelling 20-year U.S. Treasury bonds backfire? BNP Paribas warns it could worsen market sell-off; maintains prediction of 30-year yield rising to 5.8%
BNP Paribas warns that U.S. Treasury Secretary Janet Yellen should resist calls to cancel the issuance of 20-year U.S. Treasury bonds, as this measure, seemingly aimed at lowering long-term financing costs, could have the opposite effect. Not only would it be difficult to continuously suppress Treasury yields, but it could also raise borrowing costs and weaken market liquidity.
Crypto prices
More


