
Nebius Q2 Earnings Preview: AI Cloud Demand Delivery and Capacity Ramp Critical
 Bitget2026/08/12 03:29
1. Investment Highlights Snapshot
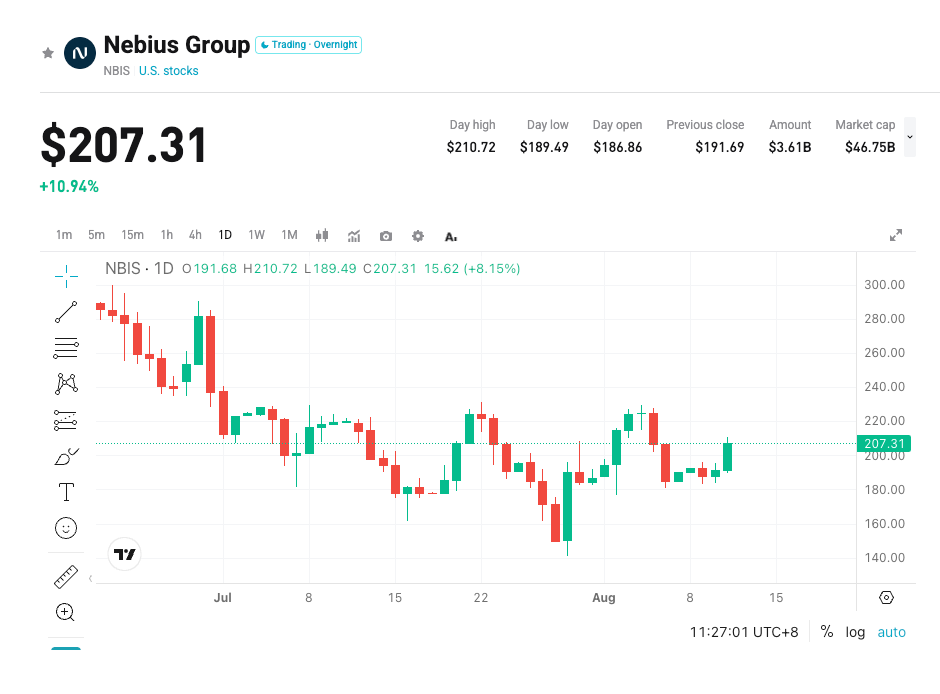
Nebius Group (NBIS.US) is scheduled to report its second-quarter 2026 results before the U.S. market open on August 12, 2026. Wall Street consensus expects revenue of approximately $570–585 million (up roughly +440% to +450% YoY) and a loss per share of about $0.70–0.75. The company previously guided for full-year revenue of $3.0–3.4 billion and is targeting annualized run-rate revenue (ARR) of $7–9 billion by year-end. After delivering $399 million in Q1 revenue (+684% YoY), the market is focused on whether the high-growth trajectory can continue, the pace of new capacity coming online, and management’s tone on the full-year outlook.
2. Four Key Focus Areas
Focus 1: Revenue Growth and Capacity Utilization
AI compute demand remains robust. Management has previously indicated that available capacity is essentially sold out even at higher pricing. Q2 is expected to show continued strong year-over-year growth. The key question is whether actual delivery and utilization rates fully match underlying demand. High utilization combined with smooth conversion of large customer contracts would reinforce the sustainability narrative.
Focus 2: Full-Year Guidance and ARR Progress
Current full-year revenue guidance stands at $3.0–3.4 billion, with a year-end ARR target of $7–9 billion. Long-term agreements already signed (including a multi-year deal with Meta valued at up to approximately $27 billion and a more than $1 billion multi-year agreement with Reflection AI) provide solid long-term visibility. Near-term revenue, however, still depends on the speed of new capacity ramps. Investors will closely watch for any upward revision to guidance.
Focus 3: Margin Pressure from Front-Loaded Investments
Management has previously signaled that adjusted EBITDA margin in Q2 may come in lower than Q1 levels. This reflects front-loaded spending on hiring, engineering, go-to-market activities, and new capabilities that are already in the cost base, while the associated capacity and revenue are still ramping. The market will assess whether gross margin and expense control remain within acceptable bounds.
Focus 4: Critical Data Center Progress and Execution Risk
Progress at key sites such as Vineland has become a point of divergence among analysts. Some firms have raised concerns that construction and power connection timelines could lag, potentially affecting 2026 growth delivery. Management’s comments on capacity online schedules during the earnings call will be a key sentiment driver.
3. Risks and Opportunities Coexist
Upside Catalysts:
- Revenue meaningfully above the consensus midpoint, with high capacity utilization and strong contract conversion validating demand resilience.
- Upward revision to full-year revenue guidance or a more constructive path toward the ARR target.
- Contained margin pressure and continued improvement in contract quality (duration and prepayment terms).
Downside Risks:
- New capacity coming online slower than expected, resulting in revenue that only meets or slightly misses the guidance midpoint.
- Adjusted margin pressure exceeding market expectations, combined with elevated capital expenditure discussions.
- Cautious commentary on key data center timelines that prompts a re-evaluation of execution capability.
4. Trading Strategy Suggestions
Bull Case: Revenue clearly exceeds consensus, capacity utilization remains elevated, and management raises or maintains an optimistic full-year outlook. This would strengthen the market’s view of Nebius as a core AI cloud infrastructure beneficiary and support valuation recovery.
Bear Case: Core metrics prove in-line or soft, clear signs of capacity delivery delays emerge, or guidance commentary turns cautious. This could trigger near-term profit-taking, particularly after the stock’s prior strong run.
Key Metrics to Watch:
- Total revenue and year-over-year growth rate
- Capacity utilization or related operating metrics
- Adjusted EBITDA margin
- Any update to full-year revenue guidance and ARR progress commentary
Operational Suggestions: If results and outlook both exceed expectations, consider positioning opportunities on post-earnings volatility. If data is neutral or execution risks rise, remain cautious of short-term swings and avoid chasing strength. Position sizing and stop-loss levels should be adjusted according to individual risk tolerance.
Stock Limited-time Offer:August new user gift: Buy U.S. stocks and get free NVIDIA stock.Trade Now for Better Deals
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
KB Home Lowers Full-Year Housing Gross Profit Margin Guidance; Shares Down Pre-Bell
London is no longer the sole stage for central bank rate meetings! The Bank of England is set to "move north" to Leeds, and the market bets on returning to the rate hike path in November.
Starting next year, the Bank of England's Monetary Policy Committee will share its responsibilities with Leeds, and the nine committee members will travel to the North to make interest rate decisions. This move coincides with Prime Minister Andy Burnham's push to prioritize the development of Northern England, and aligns with the bank's longstanding connections to Leeds, where it opened its first branch in 1827.
Uniswap Price Prediction: UNI Tests $10.96 as Open Interest Hits $971M
Chip stocks drive Nasdaq to a new high since June, Nikkei futures open higher to continue the rally: Japanese stock market set for catch-up gains tomorrow
The Japanese yen is approaching 158, and four consecutive declines have raised concerns about intervention; Japanese stocks may catch up boosted by the AI rally, but hawkish remarks from Kazuo Ueda could put pressure on Japanese bonds.
Crypto prices
More


