
SpaceX (SPCX) Q3 Earnings Preview: First Quarterly Profit and AI Self-Sustaining Validation
 2026/10/20 03:22
1. Investment Highlights
SpaceX (SPCX.US) is scheduled to release its second full earnings report since its June IPO after the U.S. market close on October 20, 2026 (Q3 results). Visible Alpha estimates Q3 revenue of $12.84 billion (more than doubling year-over-year), with the company poised to post its first quarterly profit and EPS of approximately $0.16. Wall Street consensus expects revenue of around $12.9 billion and EPS of $0.14. Of this, AI and computing is projected to contribute $6.47 billion, while Starlink is expected to contribute $4.9 billion.
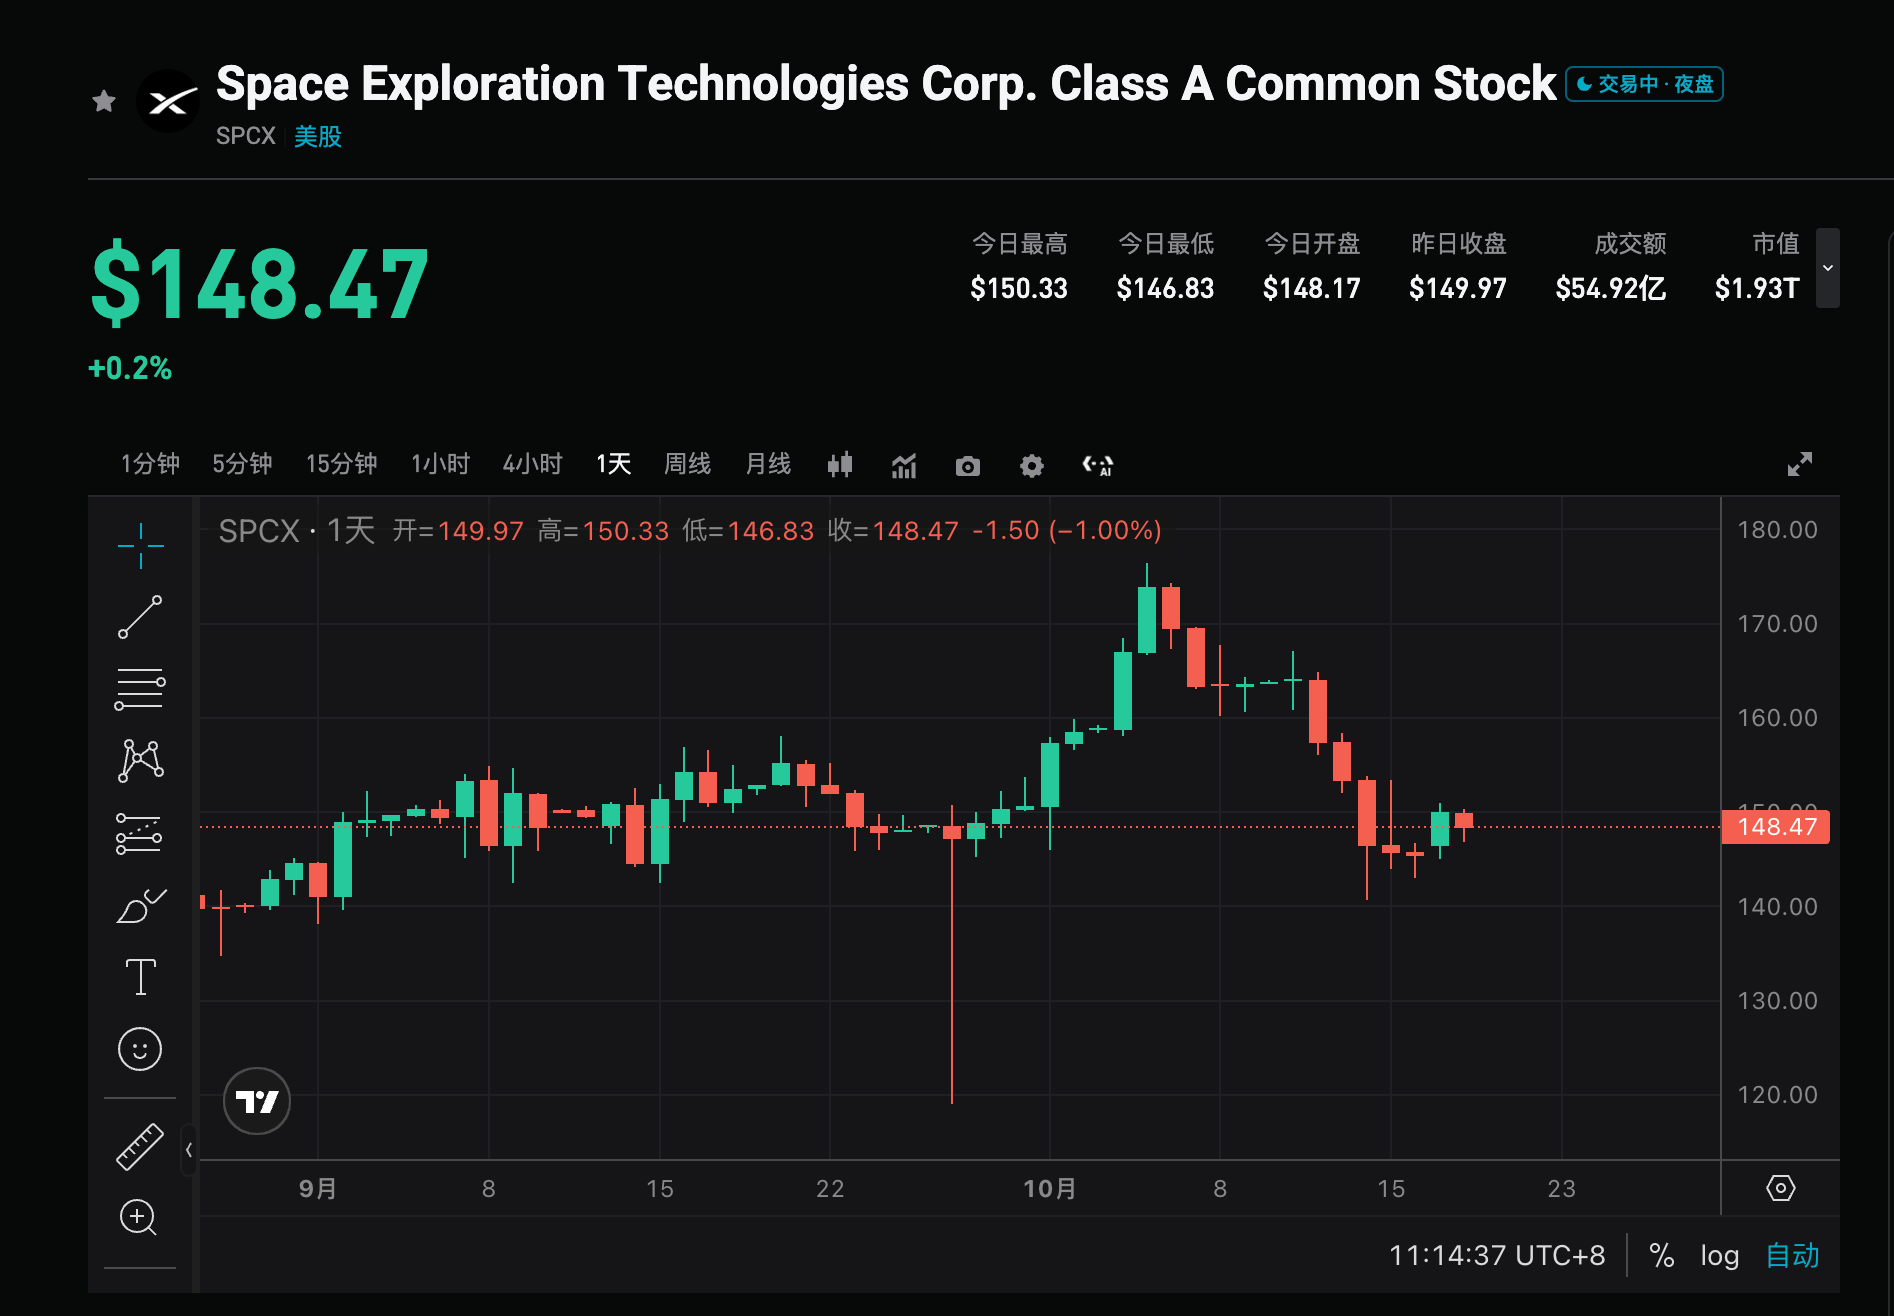
The stock is currently trading near $147.96 (up more than 10% from the IPO price, but still well below the post-listing high of $225). Options pricing implies post-earnings volatility of up to 7.5% (corresponding to a range of roughly $162 or $139). The market’s primary focus is whether AI contracts can convert into revenue at an accelerating pace and achieve self-sustaining operations rather than continuing to rely on Starlink cash flow, while also monitoring financing and lock-up considerations behind the unusually rushed earnings schedule.
Focus 1: Can the First Quarterly Profit Materialize
The market expects Q3 to mark the first profitable quarter since the IPO, a critical milestone for validating the sustainability of the business model. Both Visible Alpha and consensus point to positive EPS. Achieving this would strengthen confidence in the high-growth path; merely meeting or falling short of the low end of expectations could amplify concerns about the sustainability of elevated capital expenditures. Key thresholds are whether revenue approaches or exceeds $12.9 billion and the extent of margin improvement.
Focus 2: AI Contract Conversion Speed and Self-Sustaining Capability
AI and computing is expected to contribute nearly half of revenue (approximately $6.47 billion), making it the largest variable. Yorkville Ives and others note that stock performance is highly dependent on the pace at which contracts convert into recognized revenue. Investors want to see the AI business begin to operate on a self-sustaining basis and reduce reliance on Starlink cash flow. AI already accounted for roughly one-third of revenue in Q2; if it approaches or exceeds half in Q3, it would validate management’s earlier indication that AI revenue would surpass all other businesses and support the premium valuation narrative.
Focus 3: Stability of Starlink as the Cash Cow
Starlink is expected to contribute approximately $4.9 billion and remains the most stable profit source at present. The market will watch subscriber growth, ARPU trends, and contributions from enterprise and government customers to assess whether it can continue to provide internal funding for heavy AI capital spending. Solid growth and high margins in Starlink would ease concerns about overall cash burn; any weakness would increase dependence on external financing.
Focus 4: Financing Arrangements and Lock-Up Expiration Timing Signals
Evercore ISI analyst Kutgun Maral has noted that the rushed earnings schedule may be linked to upcoming financing or preparations ahead of lock-up expirations. The company is reportedly seeking approximately $40 billion in financing (about $10 billion in bank loans plus $30 billion in investment-grade debt) to purchase Nvidia AI chips. On October 22, 1.3 billion shares are set to come off lock-up, followed by another 329 million shares on October 24, with the remaining roughly 857 million shares still subject to a 180-day lock-up. Earnings results and management commentary could influence both financing progress and potential selling pressure from unlocked shares.
3. Risks and Opportunities
Upside Catalysts:
- Revenue and EPS meaningfully beat consensus (approaching or exceeding Visible Alpha’s $12.84 billion / $0.16), confirming the first profitable quarter and accelerating AI monetization.
- AI revenue share approaches or exceeds 50%, accompanied by management signals of self-sustaining operations and upward revisions to full-year targets.
- Stable Starlink performance, plus any progress on potential Tesla-related integration or spectrum acquisition, reinforcing the longer-term narrative.
Downside Risks:
- Results only meet or fall short of consensus, with AI contract conversion lagging and continued heavy reliance on Starlink cash flow.
- Sustained high capital expenditures, financing headwinds, or significant selling pressure from large lock-up expirations.
- Realization of the options-implied 7.5% move, combined with elevated valuation and prior gains, triggering profit-taking.
4. Trading Strategy Suggestions
Bullish Case: If revenue and earnings meaningfully beat expectations, AI monetization accelerates, and management provides a constructive self-sustaining outlook, this could reinforce the market’s view of SpaceX as an AI compute + satellite leader and support valuation recovery, particularly if positive news is digested ahead of major lock-up releases.
Bearish Risk: If results are in-line, AI continues to show heavy reliance on Starlink, or financing/lock-up pressures become more visible, the stock could face a pullback in a high-volatility environment. The options-implied 7.5% range may serve as a short-term volatility reference.
Key Metrics to Watch:
- Total revenue and year-over-year growth (consensus ~$12.9 billion)
- Whether EPS turns positive and the magnitude
- AI and computing revenue scale and mix
- Starlink revenue and related subscriber metrics
- Capital expenditures, free cash flow, and any financing-related commentary
Trading Suggestions: If results beat and the AI outlook is positive, consider opportunities on any pullback. If data is merely in-line or guidance is cautious, be mindful of short-term volatility and lock-up pressure and avoid chasing strength. Position sizing and stop-loss levels should be adjusted according to individual risk tolerance.
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
New whales now hold 33% of BTC realized cap as Strategy reduces buying
3M stock closes down 1.66% and below all three daily EMAs
JPMorgan brings JPM Coin to Ethereum
Nvidia invests billions of dollars in Germany; Jensen Huang: Once a technology powerhouse, the country has fallen behind, which pains me deeply
Nvidia signed a memorandum of cooperation with the German government at the "Invest in Germany" summit in Berlin, investing in four German startups covering robotics, healthcare, generative AI, and satellite sectors. The company also partnered with Siemens to develop AI factory solutions, potentially reducing costs by up to 20%. Jensen Huang expressed regret that Germany is lagging behind in the technology competition, noting that Europeans may be overly hesitant and consider too many factors when taking action.

Crypto prices
More


