
SpaceX Q3 2026 Earnings Highlights: Revenue Surges 161% YoY to $14.58 Billion, Super Intelligence (SI) Business Revenue Soars 830% to $7.56 Billion and Becomes the Largest Revenue Source for the First Time, Net Profit Turns Positive at $4.4 Billion.
 2026/10/21 03:04
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
Core Views
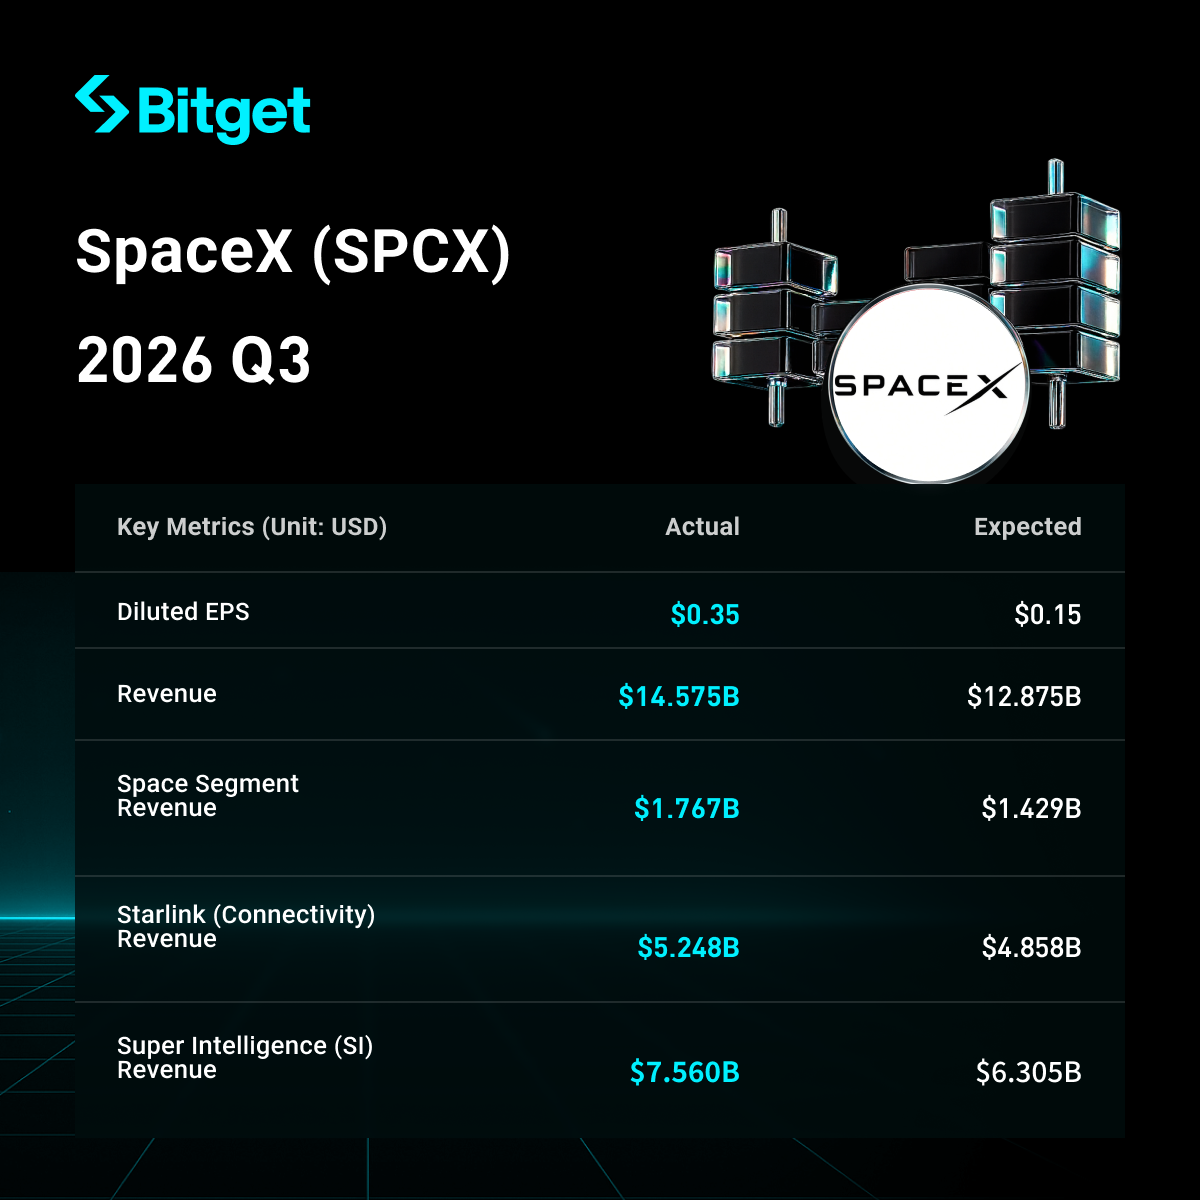
SpaceX (SPCX) released its Q3 2026 results (for the quarter ended September 30, 2026) on October 20, 2026. Revenue reached $14.58 billion, up 161% year-over-year, significantly exceeding market expectations of approximately $12.7–12.9 billion. GAAP net income was $4.4 billion, reversing a $1.1 billion net loss in the prior-year period, while adjusted EBITDA came in at $8.8 billion (+306% YoY). The Super Intelligence (SI, formerly AI) segment was the standout, with revenue soaring 830% YoY to $7.56 billion and surpassing Connectivity (Starlink) to become the company’s largest revenue source (approximately 52% of total). Growth was driven by cloud compute leasing agreements, the Cursor acquisition, and Grok products. Shares rose in after-hours trading.
Specific Breakdown
- Overall Revenue and Profit Performance
- Quarterly revenue: $14.58 billion, up 161% YoY (from approximately $5.6 billion in the prior-year quarter) and well ahead of analyst estimates of roughly $12.72–12.9 billion.
- GAAP net income: $4.4 billion (versus a $1.1 billion net loss in the year-ago quarter), an improvement of $5.5 billion.
- Income from operations: $2.8 billion.
- Adjusted EBITDA: $8.8 billion, up 306% YoY.
- Adjusted EPS: approximately $0.35 (or 45 cents), far exceeding consensus estimates of roughly $0.13–0.16.
- First nine months of 2026: cumulative net loss of approximately $413 million, with Q3 marking a clear turn to profitability.
- Super Intelligence (SI, formerly AI) Segment Performance
- Revenue: $7.56 billion, up 830% YoY (from $813 million) and up sharply from $2.561 billion in Q2, making it the company’s largest segment for the first time (approximately 51.9% of total revenue).
- Income from operations: $431 million (including roughly $1.2 billion in stock-based compensation related to the Cursor acquisition; higher excluding that charge).
- Adjusted EBITDA: approximately $5.0 billion.
- Key drivers:
- Activation of new cloud services agreements, primarily leasing compute capacity to customers including Anthropic, Google, and Reflection AI.
- Completion of the Cursor (AI coding platform) acquisition on August 14 at an implied equity valuation of approximately $60 billion; Cursor contributed $608 million in revenue during the partial quarter.
- Growing adoption of Grok models and the Grok Bot personal agent.
- Compute capacity: nameplate compute reached 1.7 GW at quarter-end (up from 0.6 GW a year earlier and 1.4 GW at the end of Q2), driven by the Colossus II data center build-out.
- SI solutions and infrastructure revenue was approximately $7.0 billion; advertising revenue was about $538 million.
- Other Business Segments
-
Connectivity (Starlink): Revenue of $5.25 billion, up 69% YoY; income from operations of approximately $2.37–2.4 billion, up 99% YoY.
- Starlink consumer subscribers: 13.6 million (up 1.6 million sequentially and roughly 89% YoY); consumer ARPU approximately $69.
- Strong enterprise and government growth; Starlink installed on more than 3,800 aircraft.
-
Space (Launch): Revenue of $1.77 billion, up 6% YoY; income from operations of a $7 million loss.
- Multiple launches completed, including Starship’s first revenue-generating mission (deploying 26 Starlink V3 satellites with roughly 10× the downlink capacity of a Falcon 9 Starlink launch).
-
Segment comparison (Q3 2026 revenue, in millions of dollars):
Segment Q3 2026 Revenue YoY Growth ShareSuper Intelligence (SI) 7,560 +830% ~52% Connectivity (Starlink) 5,248 +69% ~36% Space 1,767 +6% ~12% Total 14,575 +161% 100%
-
- Capital Expenditure Plans
- Q3 total capital expenditures: $19.6 billion, of which approximately $16.4 billion (about 84%) was related to SI/AI infrastructure, primarily for compute build-out (including Colossus facilities).
- First nine months of 2026 cumulative CapEx of approximately $48.1 billion, of which roughly $40 billion was for AI.
- Outlook: Q4 CapEx expected in the range of $35–40 billion as compute deployment accelerates.
- Compute targets: 2.5–3 GW by year-end 2026; at least +10 GW incremental in 2027 (bringing total to around 13 GW, with potential for more than 20 GW); plans for an additional 20 GW of power and cooling infrastructure.
- Management noted that new compute deployments are generating a payback of less than one year at current pricing (slightly above the high end of the $30–50 per watt range), with some scenarios potentially as short as six months.
- Versus major cloud/compute peers: SpaceX is rapidly emerging as a significant “neocloud” provider, with compute leasing revenue ramping quickly to customers including Anthropic and Google.
- Forward Guidance
- Q1 2027 total revenue guidance: $33–37 billion (well above prior market expectations of around $22 billion).
- Year-end 2026 ARR target (December run-rate): $100 billion (company reaffirmed prior guidance).
- CEO Elon Musk outlook: annual recurring revenue (ARR) of $500 billion to $1 trillion by the end of 2027.
- Other: backlog of approximately $63 billion, of which about $42 billion is expected to be recognized as revenue over the next 12 months.
- Market Context and Investor Concerns
- Core tension: SpaceX is rapidly transforming from a traditional rocket and satellite internet company into an AI infrastructure giant centered on super intelligence and compute leasing. SI has already overtaken Starlink as the largest revenue source, but elevated capital spending (potentially doubling in Q4) raises questions about cash flow and the sustainability of profitability.
- Market challenges: SpaceX’s own models such as Grok still face competition from OpenAI, Anthropic, Google, and others. Compute demand is robust (management has described being “relentlessly pursued” by hyperscalers for capacity), but large-scale deployment efficiency and payback need to be proven.
- Investor reaction: Results significantly beat expectations, particularly SI revenue and the strong Q1 2027 guidance. Shares rose in after-hours trading (reports ranging from roughly 2% to over 7%). Investors are focused on the pace of compute ramp, pricing power, and potential synergies or discussions around a possible combination with Tesla.
- Other notes: Integration of the Cursor acquisition continues; Starlink keeps expanding; Starship completed its first revenue-generating mission.
Disclaimer: This content is for reference only and does not constitute investment advice. All figures are compiled from public reports and company earnings materials; please refer to official filings for authoritative numbers.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Visa and Mesh to Expand Crypto and Stablecoin Payment Options
Market Analysis: UnitedHealth Group Stock Appears Poised to Extend Its Rally
Strong earnings boost AI stocks, US stock futures rise, SpaceX up 9% pre-market, Super Micro Computer up about 15%, oil prices rise again
Boosted by strong quarterly performances from SpaceX and Super Micro Computer, US AI-related stocks are rising in pre-market trading. Nvidia is up 1.8%, AMD is up 2.5%, and Intel is up 2.9%. SanDisk is up 2.9%, Western Digital is up 2.1%, and Seagate Technology is up 2.4%.
Crypto prices
More


