
Nonfarm payrolls greatly exceed expectations; geopolitical tensions arise; gold prices experience turmoil

FXstreet, June 5th—— Resilient to the Point of Suffocation: May Nonfarm Payrolls Soar by 172,000, Fed's "Higher for Longer" Almost a Foregone Conclusion
U.S. Bureau of Labor Statistics (BLS)
Data shows,
Amid this dual-month surge, the U.S. unemployment rate remained steady at a low 4.3% for the third month in a row.
This explosive report sent a clear and unmistakable signal to financial markets: After last year’s trough, the U.S. labor market is regaining momentum in an almost robust manner,
"Low Layoffs" Forge Ironclad Barrier; Geopolitical Oil Price Shock Yet to Emerge
Previously, the market was extremely concerned that the Iran war that broke out on February 28 (causing retail gasoline to surge over 40% and diesel to spike 55%) and negative events such as the Spirit Airlines bankruptcy would trigger a cascade of layoffs.
However, the actual data for May refuted these fears. Prominent Wall Street economists noted that the current U.S. labor market is in a rare state of “low hiring, low layoffs” with remarkable resilience:
No widespread layoffs:
The four-week moving average of initial unemployment claims also remains near historical lows, indicating that even in the face of elevated energy costs, companies still tend toward “labor hoarding”.
The hiring diffusion index improved notably: April’s prior figure was revised up by an impressive 64,000, directly overturning the earlier assumption that “the medical sector alone was propping up the job market”.
In May, hiring across more cyclical private sector industries (such as construction, manufacturing, trade, and transportation) showed broad-based recovery, proving that the economy is not being artificially propped up but carries genuine endogenous momentum.
Wages and Inflation Face Off at High Levels, "Real Purchasing Power" Undercurrent Surges
On the wage front, May’s average hourly earnings rose 3.4% year-on-year (month-on-month +0.3%). Although this pace has eased somewhat from post-pandemic highs, under the current high-inflation environment, it is seen as a “double-edged sword” in the eyes of the Fed.
On one hand,
On the other hand, hawkish officials like Fed Governor Cook and Cleveland Fed President Mester argue that, with trillions in AI investments driving up chips and data centers and geopolitical crises lifting oil prices, wage growth as high as 3.4% can easily resonate with imported inflation—triggering the market’s greatest fear, the “wage-inflation spiral”.
Policy Space Fully Open—The Fed Hawks Hold All the Leverage
This blowout nonfarm report undeniably sets a decisively hawkish tone for the Fed’s upcoming June policy meeting.
It not only fully dismisses any near-term prospect of a “rate cut”, but even pushes the market onto the ironclad path of “higher for longer” interest rates.
Economic “resilience” provides the Fed with a broader moat: Robust job growth confirms that the real economy has not been crushed by high interest rates.
This means that, as the Fed embarks on a “protracted war” against Iran-war-driven imported inflation, it has more than enough room to keep rates high for longer without fearing an abrupt economic downturn.
The invisible door to renewed rate hikes is ajar: Following the data release, Wall Street swap markets quickly repriced the policy path. Some aggressive macro hedge fund analysts suggest that if next week’s May CPI inflation reading also strengthens (following PPI), this “superheated” jobs data will not just support a “hold” on rates but could force the Fed to revisit the question of “whether further rate hikes are needed” in the second half.
Conclusion & Market Outlook: Gold Bull Run Hit by "Hawkish Blitz", Resilient Nonfarm Topples Bulls' Defenses
This blowout result of 172,000 (with a major upward revision to the previous figure) directly slashed gold’s near-term upside potential.
“Heavy blow” from surging real rates: Strong job growth has utterly shattered the Fed’s recent rate cut hopes, and swap markets’ expectations for “higher for longer” rates have been pushed out again.
This has directly lifted U.S. Treasury real yields and strongly boosted the dollar, putting enormous selling pressure on zero-yield assets—namely, gold.
Looking ahead, gold is now locked in a tug-of-war between “geopolitical premium” and “the Fed’s iron fist”.
Although the supply chain crisis and wholesale inflation (PPI at 6%) from the Iran war still provide long-term inflation-hedge support for gold, in the summer of 2026, as long as this exuberant jobs report keeps the Fed glued to its “fighting inflation to the end” hiking cycle, there will always be a sword hanging over gold’s upside.
Whether gold bulls can mount an effective counterattack will depend on the May CPI data to be released next week—if it triggers the Fed’s “rate hike restart” ultimate alarm.
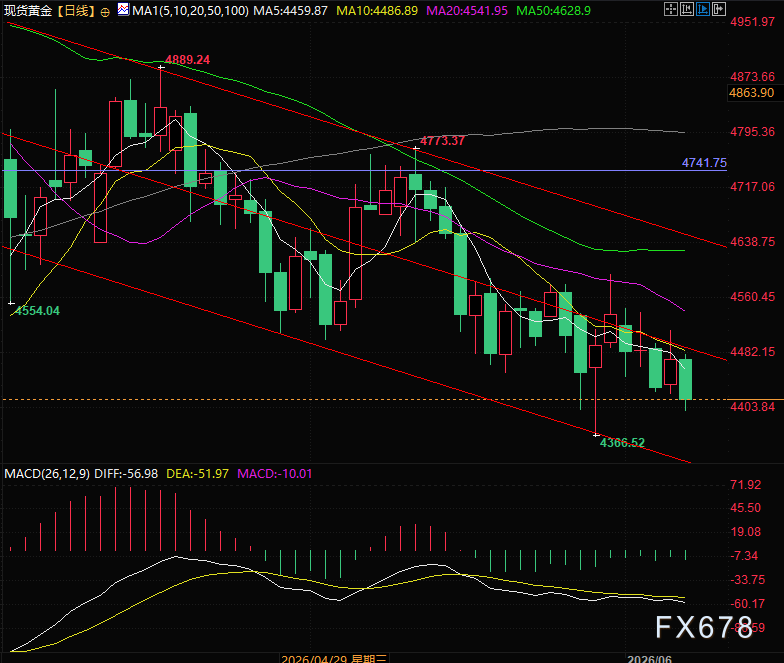
(Spot gold daily chart, source: Easy Forex)
Beijing Time (UTC+8) 21:17: Spot gold currently at $4,416/oz.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Gold falls below $4,200: Triple pressures rise, bears eye $4,000 or even $3,800
Trump Rejects Iran's Proposal for Talks; Global Stocks and Bonds Under Pressure, Oil Prices Up Over 2%, Gold Falls Below 4200
Trump rejected Iran's latest proposal to reopen the Strait of Hormuz, causing the optimistic sentiment in the market last Friday to quickly reverse amidst the Middle East diplomatic stalemate. Brent crude oil rose over 2%, gold fell below $4,200, and silver dropped more than 4%. Asia-Pacific stock markets broadly declined, with South Korea's KOSPI falling over 2%. Global bond markets came under pressure, and the yield on the US 2-year Treasury rose to 4.90%. Market focus will shift to this week's PCE inflation data and the non-farm payroll report.
Indian Rupee starts the week negatively amid higher oil prices
AI demand drives TSMC to accelerate capacity expansion, 2nm monthly production aims for 120,000 wafers by year-end
According to reports, industry giants such as Apple, Nvidia, and AMD have collectively increased their orders by 10% to 20%, directly boosting TSMC's 2nm monthly production capacity to 120,000 wafers by the end of the year, which exceeds the previous estimate by more than 20% and brings forward the 2027 target by two years. For the first time in history, five factories will ramp up production simultaneously, and the annual compound growth rate of capacity from 2026 to 2028 will reach as high as 70%.
Crypto prices
More


